
We’re not for everyone.We’re for capital with consequences.
Once capital becomes difficult to replace, it deserves a different kind of advice.
We manage the investments.We advise the family.We coordinate everything else.
Shell Capital manages client portfolios held independently, in your name, at Goldman Sachs. They provide custody, trade execution and reporting. We make the investment decisions, as an independent fiduciary and registered investment adviser since 2004.
Skew the payoff in your favor.
Some money is different.
When the capital changes, the job changes. For years, the business, the practice or the career created the capital. Then something happens, and the capital itself has a different job: fund a life for decades, hold up through markets no one can predict, stay available for the next opportunity, and eventually pass to someone else.
You sold the business.
The first capital you’ve held that you didn’t control day to day. What it does next is a portfolio decision, not an operating one.
You’re preparing to exit.
The largest asymmetric trade you’ll make, made once. Bring it to us before the terms are set.
Your wealth is one stock.
The upside made you. The downside can undo decades in a quarter.
The portfolio is the paycheck now.
No more contributions. A bad stretch early costs more than the averages show.
You inherited it, or hold it in trust.
Someone else’s life’s work, and a duty that outlasts markets.
It’s decades of earnings.
A profit-sharing plan, a rollover, a lifetime of saved income. It doesn’t need to be doubled. It needs to survive what it’s about to see.
At that point, managing a portfolio isn’t enough. The whole financial life has to work together. This is the moment we’re built for.
You probably already have an adviser.
Most successful people do. The question isn’t whether you have someone. It’s whether the advice, the portfolio and the risk discipline you have today were built for the capital and the consequences you have now.
Sometimes the answer isn’t moving everything. It may be improving the investment mandate, solving one particular risk, or coordinating what isn’t being coordinated.
You don’t have to move everything to have that conversation.
Two principals. One strategy. One family.
ASYMMETRY® is the discipline. Shell Capital Management is the firm behind it. You don’t meet a salesperson and get handed to someone else. You work directly with Mike and Christi Shell.
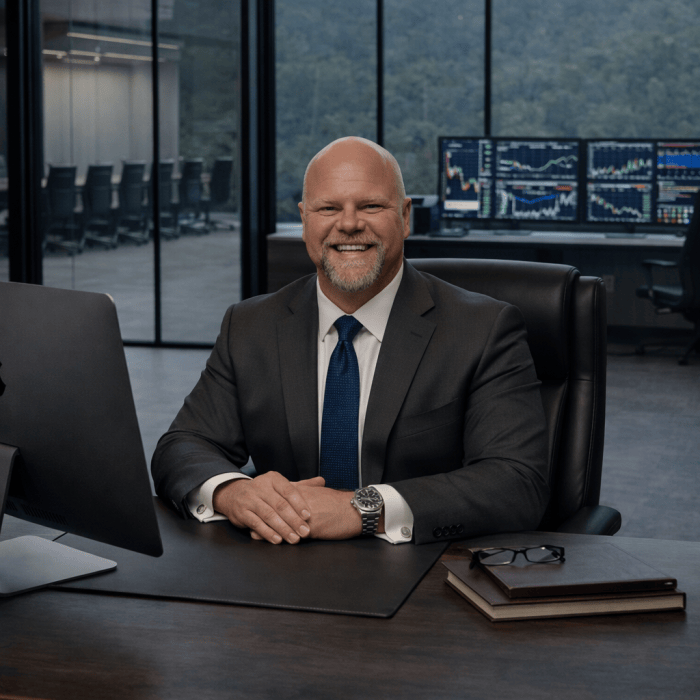
Mike Shell
Founder & Chief Investment Officer
Mike has actively managed money and risk through every boom and crash since the 1990s. He founded Shell Capital in 2004, develops and runs the systems behind ASYMMETRY®, manages client portfolios personally, and runs his own capital under the same discipline. Marine Corps veteran. The methods have evolved. The principle hasn’t.
Meet Mike
Christi Shell
Director of Private Wealth Strategy
Christi is the family’s adviser and wealth manager. She leads the planning, coordination and execution around the capital — estate, tax, trusts, retirement, liquidity, insurance, asset protection, business interests and family priorities — so the decisions that usually get handled separately work as one.
Meet ChristiWe both understand your financial life. We’re both in the room for the consequential decisions. The investment strategy and the wealth strategy are built toward the same outcome, not managed in separate rooms.
We’re a fiduciary money manager, not a brokerage or a bank. Our clients don’t talk to an assistant or a junior adviser. They talk to us. That’s why we limit who we work with, and how many: people who have already made it and intend to keep it, and to survive and thrive through whatever comes next.
Your wealth is one system.
- A portfolio can be well managed while the family balance sheet is poorly managed.
- A good investment decision can create an unnecessary tax problem.
- An estate strategy can change liquidity needs.
- A trust can change how assets should be invested.
- A business sale can change almost everything at once.
That’s why we look at the whole picture: investments, tax, estate and wealth transfer, trusts, liquidity and credit, insurance, business interests, philanthropy, family and legacy. Coordinated with your CPA, attorney and trustee, not in place of them. Not every family needs every capability. That’s the point: the relationship is shaped to the family, not the family to a service model.
Family-office capabilities, with or without the family office.
As capital grows, so does everything around it: entities, accounts, trusts, private investments, people, decisions. At some point the problem isn’t another investment. It’s coordination. Most families get family-office capabilities around the advisory relationship without building one: consolidated reporting, entity accounting, cash management, bill pay, trust and tax-document coordination. Families who want a formal family office get one built and run properly, with the same fund-administration firms that keep the books for hedge funds handling the accounting and back office. And when a family needs a corporate trustee, we work with independent trust companies and our custodian’s trust resources, so the trustee handles fiduciary administration while we keep managing the investments and advising the family.
Every wealth decision is a bet.
Each one has a cost you can define in advance and an outcome you can’t. We size the cost, keep the outcome open, and don’t let one decision put the whole picture at risk.
Asymmetric risk and reward. Applied to the whole balance sheet.
Investment management is different here.
Most wealth-management firms are built around advice and an asset allocation. We’re also investment portfolio managers. That distinction matters. The first question we ask about an investment isn’t how much we can make. It’s what happens if we’re wrong.
How much could your portfolio decline before you’d tap out?
Risk tolerance isn’t a questionnaire. It’s a dollar boundary: the decline large enough to change your behavior. We define it first, then manage the portfolio to respect it.
How much total return do you want or need over a full market cycle?
Returns only count across a complete cycle, bull and bear. Your answer sets the objective the portfolio is engineered to pursue. No benchmark hugging. No relative-return alibi.
Every position enters with its exit already defined — the downside decided before entry, in dollars. Losses cut short. Winners given room. Exposure rotated as the evidence changes, not allocated once and left alone. Compounded across a full market cycle, that shape is the objective.
Rotate, not allocate. Manage the risk you actually have.
Losses hurt more than gains feel good. Losing $1,000,000 feels about 2.25 times as bad as gaining $1,000,000 feels good: −2.25 against +1.0 on the same scale. To feel as good as that loss feels bad, the gain would have to be about $2,500,000. Prospect Theory value function, Tversky–Kahneman (1992): α = 0.88, λ = 2.25. Nobel Prize in Economic Sciences. © Shell Capital Management, LLC
Losses compound against you. Recovery is not symmetrical, which is why drawdown control is the central task. R = L ÷ (1 − L). Arithmetic, not opinion. © Shell Capital Management, LLC
You built the capital by taking risk. Now every risk has to earn its place. We’d rather never need the 100%.
Alternative investments, in-house.
We run our own alternative strategies: separate sources of return, designed to make money in conditions that hurt a conventional portfolio, so the outcome doesn’t rest on one bet. When another manager has an edge we don’t, we do the research and due diligence to access it. Nothing is off the table, and everything has to earn its place.
ASYMMETRY® Portfolio Hedging.
Some capital can’t move, or shouldn’t: company stock, a legacy account, an inherited position, a portfolio you’re not ready to change. For $5 million or more, we can hedge it where it sits, with the same discipline: the downside defined, the upside left open.
Significant wealth asks different questions.
Not: what’s the best stock? But:
- How much capital should remain exposed to market risk?
- How much liquidity do we actually need?
- Where are we unintentionally concentrated?
- Should I sell, hedge, borrow against, or keep this position?
- What should be gifted now rather than later?
- What happens to my spouse if I’m not here?
- What does the estate plan actually do if I die tomorrow?
- How much is enough, and what is this money ultimately for?
Those aren’t portfolio questions. They’re wealth questions. We answer both.
Independent judgment. Institutional custody.
Being independent doesn’t mean operating alone. Your accounts are held in your name at Goldman Sachs Custody Solutions, which holds the assets, executes the trades, and reports to you independently. We make the investment decisions under the authority you grant. Our alternative strategies are our own; when an outside manager or specialist can improve the outcome enough to justify the cost, complexity and risk, we bring them in. Access doesn’t determine the recommendation. We do.
Goldman Sachs Custody Solutions is an independent custodian. It does not own, supervise, or endorse Shell Capital Management, LLC.
What we don’t do.
- We don’t sell anything. We advise and manage.
- We aren’t captive to a bank, a broker-dealer, an insurance company, a product manufacturer or a single platform.
- We don’t hand you off.The people you read here are the people responsible for the work.
- We don’t hug a benchmark.Losing less than an index is still losing.
- We don’t forecast.We respond to evidence.
- We don’t replace your CPA, attorney or trustee.We coordinate them. If you don’t have one yet, we help you find one, vet them, and give you options.
- We don’t pretend to be the fit for everyone.If we aren’t, we say so and point you to someone who is.
What working with us looks like.
- 01Understand.It starts with a private conversation. You write; Mike or Christi reads it and replies. What changed? What does the money need to do now? What concerns you? What’s handled well today, and what’s missing?
- 02See the whole picture.We map the family balance sheet — investments, business, real estate, retirement assets, trusts, entities, liabilities, insurance, cash flows, the professionals already in place — and find where the real risks and opportunities are.
- 03Build the strategy.Your two answers set the portfolio’s objective, and the wealth strategy is built around it. What stays liquid. What gets invested. Which risks deserve exposure. Which don’t. What happens first.
- 04Implement.We manage the investments directly, in your name at Goldman Sachs, and coordinate the rest with your CPA, attorney, trustee and lender. No binder on a shelf. Decisions get assigned, executed, tracked and documented in writing.
- 05Keep it current.Markets change. Tax law changes. Families change. We review the portfolio, the balance sheet, the major risks and the open decisions together, and the strategy evolves with them.
Wealth management isn’t an event. It’s an operating system.
Systematic doesn’t mean automatic. Quantitative discipline. Human accountability.
We publish what we see, as we see it.
Read enough and you’ll know whether our way of thinking makes sense to you before we ever speak. That’s the point.
ASYMMETRY® Observations
Mike on markets, risk, exits, position sizing, drawdowns and optionality. On the record.
Read ASYMMETRY® ObservationsPrivate Wealth Strategist
Christi on business exits, retirement income, estate, trusts, tax-aware strategy and the family decisions around the capital.
Is this for you?
Our work is for investors and families with $5 million or more in investable capital, including those approaching a sale, retirement or rollover that will put them there. It’s built for people who have reached the point where the money is meaningful, the decisions interact, and getting it wrong can cost more than investment performance.
- You should know who is managing your capital.
- You should know why you own what you own.
- You should understand the important risks.
- Your CPA, attorney, trustee and adviser should not be solving different versions of the same problem.
- And when the situation changes, someone should be responsible for seeing the whole thing.
Who is this for?
Investors and families with $5 million or more in investable capital, and those approaching a sale, retirement or rollover that will put them there. Fit matters more than the number: if that’s where you’re headed, write to us.
Do you do everything, or only the investments?
Both. We manage the capital, we advise the family across the whole financial picture, and we coordinate your CPA, attorney, trustee and lender so the decisions work as one.
Where is my money held?
In your name at Goldman Sachs Custody Solutions, which provides custody, trade execution and reporting. We don’t take custody. We make the investment decisions under the authority you grant.
Who actually manages it?
Mike Shell, personally, with the same discipline he applies to his own capital. There is no handoff to a team you haven’t met.
What does it cost?
Fees are disclosed in our Form ADV and discussed plainly in the first conversation, before you commit to anything.
Do I keep my CPA and attorney?
Yes. We coordinate with them; we don’t replace them. If you don’t have a CPA, attorney or trustee yet, we help you find one, vet them, and give you options.
Do I have to move everything?
You don’t have to move anything to have the conversation. Sometimes the answer is one account, one risk, or one decision. A portfolio you can’t move can be hedged where it sits. What makes sense after that depends on what the capital has to do.
What happens when I reach out?
You write. Mike or Christi reads it personally and replies in writing. Then a private conversation, confidential and unhurried, honest in both directions. If we aren’t the fit, we say so and point you to someone who is.
Bring us the consequential decision before you make it.
Tell us what’s happening. A business sale. Retirement. Concentrated stock. An inheritance. A portfolio that no longer makes sense. A financial life that has become too complex to manage in pieces. We’ll listen first. If we believe we can materially improve the situation, we’ll explain how. If we don’t, we’ll tell you that too.
I’ve managed money through every kind of market since the 1990s, and I manage my own the same way I manage yours. If you write, I’ll read it myself.
Mike Shell, Founder & Chief Investment Officer
Shell Capital manages client portfolios held independently, in your name, at Goldman Sachs. They provide custody, trade execution and reporting. We make the investment decisions, as an independent fiduciary and registered investment adviser since 2004.
Shell Capital Management, LLC is an independent, fiduciary registered investment adviser founded in 2004 and headquartered in Knoxville, Tennessee, serving families across East Tennessee — Knoxville, Chattanooga, Cleveland, and Athens — and throughout the United States. Through ASYMMETRY® Managed Portfolios, alternative investments, and ASYMMETRY® Wealth Strategy, the firm provides private wealth management to business owners, physicians, executives, retirees, and families with capital that carries consequences. Client assets are custodied at Goldman Sachs Custody Solutions.